FAB Mortgage Rate UAE 2026: Current Rates, Eligibility, Fees & EMI
If you are searching for the FAB mortgage rate in the UAE, there is one number you should not look at alone.
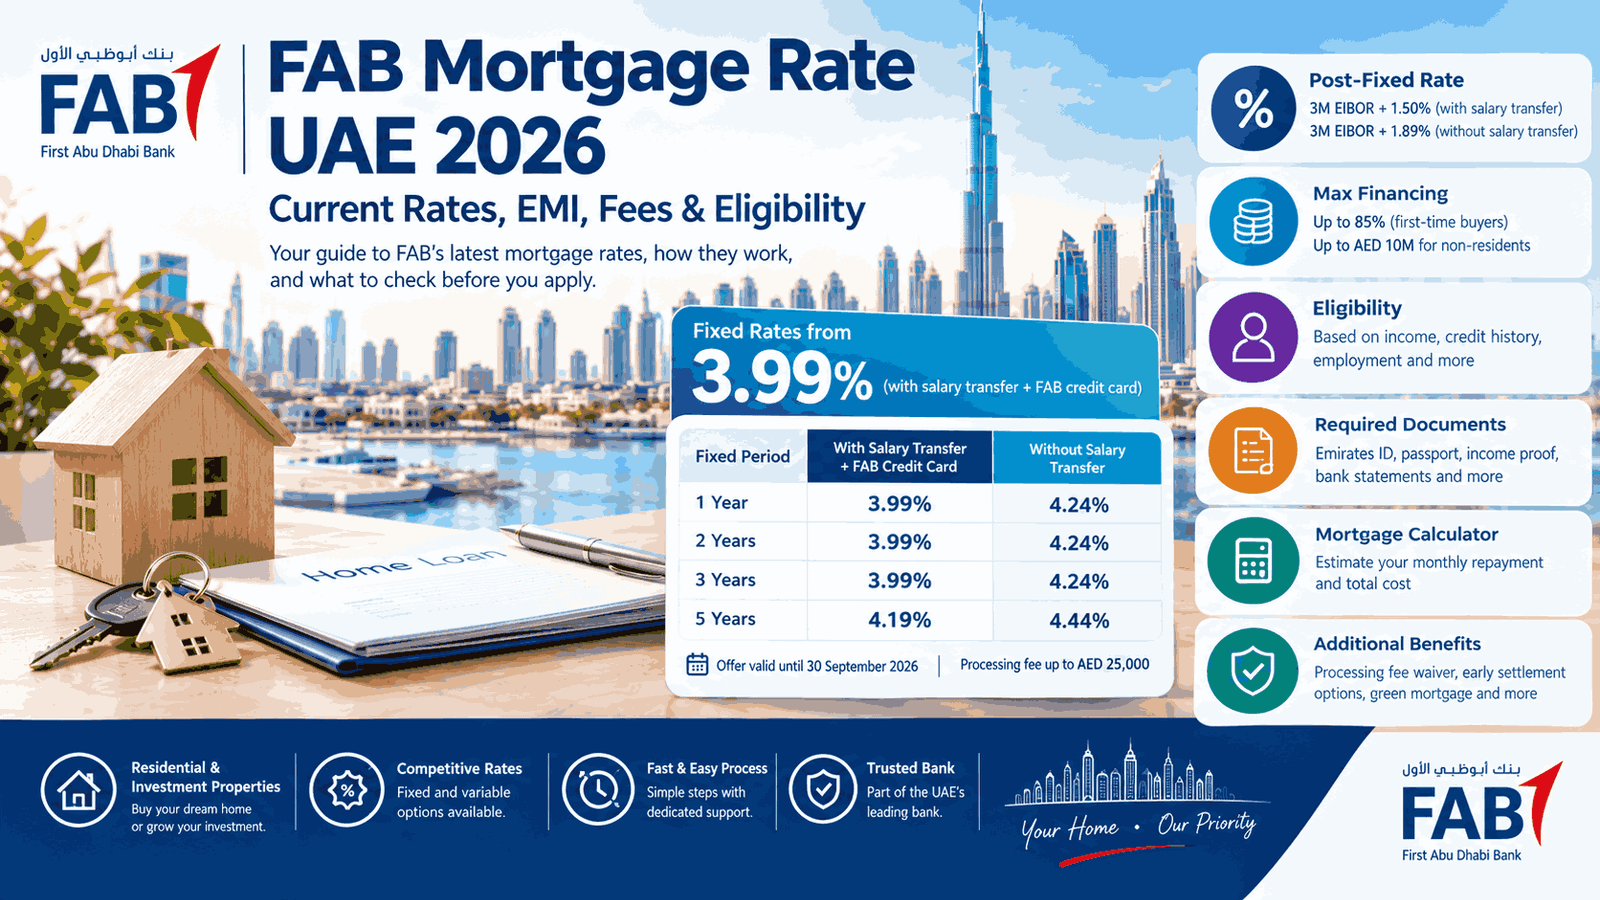
FAB currently advertises fixed mortgage rates starting from 3.99%, but the rate you receive depends on factors such as whether you transfer your salary to FAB, whether you take a FAB credit card, the fixed period you choose, your application profile and the terms offered by the bank.
There is another important point: the advertised fixed rate only applies for the selected fixed-rate period. After that period, your mortgage can move to a variable rate based on the terms of your mortgage agreement.
Here is how the current FAB mortgage rates work, what you may need to qualify, and what to check before signing.
Safety note: A mortgage is a long-term financial commitment. Check the current rate, Key Facts Statement, Mortgage Terms and Conditions, processing fees, valuation charges, insurance, early-settlement terms and the rate that applies after the fixed period directly with FAB before applying. Never share your banking password, OTP, PIN or full card details with anyone claiming to arrange your mortgage.
FAB Mortgage Rate Today
For new FAB mortgage customers, the bank currently publishes the following fixed-rate options for UAE residential mortgages:
| Fixed period | With salary transfer + FAB credit card | Without salary transfer |
|---|---|---|
| 1 year | 3.99% | 4.24% |
| 2 years | 3.99% | 4.24% |
| 3 years | 3.99% | 4.24% |
| 5 years | 4.19% | 4.44% |
These are the rates currently published by FAB for fresh mortgage customers. The offer is subject to conditions, and the bank states that the rates for existing FAB mortgage customers can differ according to their existing mortgage contract and terms.
The current processing-fee campaign is also time-sensitive: FAB says the offer is valid until 30 September 2026 and is capped at AED 25,000.
What Does “3.99% FAB Mortgage Rate” Actually Mean?
This is where many mortgage searches become confusing.
The 3.99% rate is not a lifetime mortgage rate.
It applies to the applicable fixed-rate period selected by the customer.
For example, a qualifying customer could have a 3-year fixed period at 3.99%. Once that period ends, the mortgage moves to the applicable subsequent variable-rate arrangement stated in the mortgage agreement.
FAB currently says that, for customers transferring their salary to a FAB account and taking a FAB credit card, the subsequent rate is equivalent to 3-month EIBOR + 1.50%, subject to the stated minimum-rate condition. For customers without salary transfer, FAB currently publishes 3-month EIBOR + 1.89%, also subject to the stated minimum.
That means you should never compare mortgages using only the introductory fixed rate.
The post-fixed-period formula can be just as important.
FAB Mortgage Rate With Salary Transfer
The current FAB pricing gives a lower published fixed rate to customers who:
- Transfer their salary to a FAB account, and
- Choose a FAB credit card.
Under the current offer:
- 1-year fixed: 3.99%
- 2-year fixed: 3.99%
- 3-year fixed: 3.99%
- 5-year fixed: 4.19%
Without salary transfer, the published rates are:
- 1-year fixed: 4.24%
- 2-year fixed: 4.24%
- 3-year fixed: 4.24%
- 5-year fixed: 4.44%
This creates an important calculation for borrowers.
If you already receive your salary through FAB and use a FAB credit card, the advertised rate may be different from the rate available to a customer who does not transfer salary.
But don’t look at the rate difference alone.
Also calculate the cost and conditions attached to the salary-transfer and credit-card arrangement.
FAB Mortgage Fixed Rate vs Variable Rate
A fixed rate gives you greater payment predictability during the fixed period.
If your rate is fixed for three years, for example, your mortgage pricing does not move with EIBOR during that agreed fixed period.
Afterward, the mortgage can move to a variable rate according to the contract.
FAB also publishes a current variable-rate reference of 3-month EIBOR plus a margin of 1.49%, with a minimum rate of 1.99%, on its existing-homeowner mortgage information page. However, the exact rate applicable to your mortgage depends on the product and contract, so this should not be substituted for the rate stated in your own offer.
This is why asking the bank only:
“What is your mortgage rate?”
is not enough.
Ask:
“What rate will I pay after my fixed period ends?”
That answer can make a significant difference over a long mortgage.
How Much Can You Borrow From FAB?
FAB says eligible first-time buyers can receive financing of up to 85% of the property value, subject to the applicable conditions.
The amount you can actually borrow depends on your circumstances, including income, existing financial commitments, property value, credit profile and the bank’s affordability assessment.
The advertised maximum financing percentage does not mean every applicant will automatically receive that percentage.
Your required down payment therefore depends on the transaction and your approved financing amount.
FAB Mortgage for Expats
FAB offers mortgage financing for expatriates buying residential property in the UAE.
The bank currently publishes different grace periods and mortgage-buyout conditions for UAE Nationals and expatriates.
For expatriates, FAB currently lists:
- 60 days grace period for new mortgages
- 120 days for mortgage buyouts
The current offer also provides processing-fee waivers for qualifying salary-transfer customers under the stated campaign conditions.
Your actual approval, loan amount, rate and required documents are determined after the bank assesses your application.
FAB Mortgage for UAE Nationals
FAB also has mortgage products for UAE Nationals.
Under the current standard mortgage offer, FAB lists:
- 90 days grace period for new mortgages
- 180 days for mortgage buyouts
Processing-fee benefits can also apply to qualifying salary-transfer customers.
UAE Nationals may also have access to separate housing-finance products, so it is worth checking the exact product rather than assuming the standard residential mortgage is the only option.
FAB Mortgage for Non-Residents
FAB also provides mortgage financing for non-UAE residents purchasing investment property in the UAE.
The bank currently states that non-UAE residents can borrow up to AED 10 million, with financing of up to 50% of the property’s value, subject to the applicable requirements.
FAB also says these mortgages can have variable rates linked to either EIBOR or MBR.
This is significantly different from the standard UAE-resident mortgage offer.
If you live outside the UAE, don’t use the resident mortgage rates as your expected rate.
Ask for a non-resident quotation specifically.
FAB Mortgage Calculator
FAB provides a mortgage calculator on its official website.
You can enter:
- Property price
- Down payment
- Mortgage period
- Annual interest rate
The calculator then estimates:
- Mortgage amount
- Monthly repayment
- Indicative repayment schedule
FAB specifically notes that the calculator is an estimate and that the down payment depends on the transaction type and applicable conditions.
This is useful before speaking to a mortgage adviser because you can test different down payments and fixed rates.
Example: How the FAB Mortgage Rate Affects Your EMI
Suppose you borrow AED 1,000,000.
At a fixed annual rate of 3.99%, a 20-year repayment period would produce an indicative monthly principal-and-interest payment of roughly AED 6,055.
At 4.44%, the same AED 1 million over 20 years would be roughly AED 6,289 per month.
That difference is about AED 234 every month.
Over several years, even a relatively small rate difference can therefore become meaningful.
These are illustrative calculations, not a FAB quotation. Your actual repayment can differ because of the approved rate, tenure, insurance and other applicable charges.
FAB Mortgage Processing Fees
Mortgage cost is not just the interest rate.
FAB currently states that qualifying first-time buyers and customers making developer handover payments can receive processing-fee waivers under the current campaign.
The current campaign is capped at AED 25,000 and is stated as valid until 30 September 2026. Non-salaried customers receive a 50% discount under the published conditions.
This is important if you are comparing FAB with another bank.
A bank offering a slightly lower rate may not necessarily have the lower overall cost once you add:
- Processing fee
- Property valuation
- Insurance
- Early settlement cost
- Mortgage registration expenses
- Other bank charges
Compare the complete cost, not just the headline rate.
Can You Pay Extra on a FAB Mortgage?
FAB currently states that during the variable-rate period, customers can make a partial settlement of up to 25% of the outstanding loan annually without fees, subject to the applicable conditions.
This can matter if you expect to receive:
- Annual bonuses
- Business income
- Investment proceeds
- Property-sale proceeds
- Other large cash amounts
Paying additional principal can reduce the outstanding balance and potentially reduce the future financing cost.
However, check the terms before making an extra payment because the rules can differ depending on the stage of your mortgage.
FAB Mortgage Buyout
If you already have a mortgage with another UAE bank, FAB also offers mortgage-transfer or buyout options.
The current FAB offer states that qualifying mortgage transfers can receive:
- Processing-fee waiver
- Valuation-fee waiver
- Refund of eligible early-settlement fees
- A grace period before the first instalment
FAB currently publishes a 180-day grace period for UAE Nationals and 120 days for expatriates for mortgage buyouts.
This can make a mortgage transfer worth investigating if your current bank’s rate or terms have become less suitable.
But calculate the complete cost of transferring before making the decision.
FAB Green Mortgage
FAB also offers a Green Mortgage for qualifying sustainable properties.
The bank states that eligible properties can qualify based on recognised sustainability certifications such as:
- LEED Silver or above
- BREEAM Good or above
- Estidama 2 Pearls or above
- HQE Good or above
- CASBEE B+ Good
- Green Star 4 Stars
The Green Mortgage page also refers to additional discounts or waivers relating to processing, valuation, insurance and partial settlement, subject to the product conditions.
If you are buying a certified sustainable property, it is worth asking FAB whether the property qualifies before applying for a standard mortgage.
FAB Mortgage Application Process
The basic process starts with checking how much you can afford.
FAB’s published mortgage process includes the following stages:
1. Check Your Budget
Use the FAB mortgage calculator to estimate your monthly repayment.
Don’t base your budget on the maximum amount the bank may approve.
Leave room for:
- Service charges
- Maintenance
- Insurance
- Utilities
- Property-related expenses
- Existing loans and credit cards
2. Request an Approval in Principle
FAB says customers can speak with a mortgage specialist and apply for an approval in principle to estimate their borrowing eligibility.
An approval in principle can give you a clearer budget before negotiating on a property.
3. Find the Property
Once you have identified the property, FAB’s published process includes signing the relevant MOU and arranging a property valuation.
4. Submit Your Documents
The bank may request documents such as:
- Mortgage application form
- Income proof
- Sale and purchase agreement
- Identification documents
- Other documents requested by the mortgage specialist
The exact documents depend on your application and property.
5. Property Valuation
The property needs to be assessed as part of the mortgage process.
The valuation is important because the bank’s financing amount is linked to the property’s accepted value and the applicable loan-to-value conditions.
6. Final Approval and Offer
If approved, you receive the mortgage offer and relevant terms.
Read the fixed-rate period, subsequent variable rate, fees and early-settlement conditions before signing.
7. Registration and Disbursement
The final stage involves completing the required property and mortgage registration steps before the loan is disbursed.
What Salary Do You Need for a FAB Mortgage?
There isn’t one simple salary number that applies to every FAB mortgage.
Mortgage approval is based on your overall financial profile rather than salary alone.
The bank can consider:
- Monthly income
- Existing loans
- Credit-card commitments
- Employment
- Length of employment
- Credit history
- Property value
- Down payment
- Age
- Other financial commitments
This is why someone earning the same salary as another applicant can receive a different approved mortgage amount.
What Documents Do You Need?
The exact list depends on your situation, but you should expect to provide documentation relating to:
- Identity
- Residence status
- Employment
- Income
- Bank accounts
- Existing liabilities
- Property purchase
FAB’s published mortgage application process specifically refers to income proof, the sale and purchase agreement and other documents requested by the mortgage specialist.
Prepare your documents early if you are working against a property-purchase deadline.
The Question You Should Ask FAB Before Signing
Don’t ask only:
“What is the mortgage rate?”
Ask these instead:
What is my fixed rate?
How long is the fixed period?
What rate applies after the fixed period?
Is the subsequent rate based on EIBOR, MBR or another formula?
What is the margin over the benchmark?
Is there a minimum rate?
What is the processing fee?
What is the valuation fee?
What insurance is required?
What happens if I settle early?
How much can I partially settle each year without a fee?
What happens if I transfer my salary?
Do I need a FAB credit card to receive the advertised rate?
These questions are much more useful than comparing two advertisements based only on their starting percentages.
Is the Lowest FAB Mortgage Rate Always the Cheapest Option?
Not necessarily.
Imagine two offers:
| Cost | Offer A | Offer B |
|---|---|---|
| Initial fixed rate | 3.99% | 4.24% |
| Fixed period | 3 years | 3 years |
| Processing fee | Lower | Higher |
| Salary transfer | Required | Not required |
| Credit card | Required | Not required |
| Post-fixed rate | Check contract | Check contract |
| Early settlement | Check terms | Check terms |
Offer A may look cheaper immediately.
But if you do not want to transfer your salary or maintain another product, the practical cost may be different.
The only reliable comparison is the total cost over the period you expect to keep the mortgage.
FAB Mortgage Rate: What to Check in 2026
The current published FAB mortgage offer is particularly important to check before applying because rates and promotional conditions can change.
As of the latest FAB information available, the advertised fixed rates for new customers start at 3.99% with salary transfer plus a FAB credit card.
Without salary transfer, the published starting rate is 4.24% for the 1-, 2- and 3-year fixed options.
For the 5-year fixed option, the published rates are 4.19% with salary transfer plus a FAB credit card and 4.44% without salary transfer.
The current processing-fee campaign is stated to run until 30 September 2026, so this particular offer should not be treated as a permanent FAB mortgage rate.
Final Check Before Applying for a FAB Mortgage
Before you apply, write down these seven numbers:
- Property price
- Your down payment
- Required mortgage amount
- Fixed mortgage rate
- Fixed-rate period
- Rate after the fixed period
- Estimated monthly repayment
Then add the fees and insurance.
That gives you a much more realistic picture than simply seeing “FAB mortgage rate from 3.99%” in an advertisement.
FAB’s own mortgage calculator can be used to estimate the mortgage amount and monthly repayment, while the bank’s mortgage documentation should be used for the final contractual terms.
For UAE homebuyers, TheUAEWeb.com focuses on practical banking and finance information so you can understand the important numbers before committing to a long-term financial product.
FAQs About FAB Mortgage Rate
What is the current FAB mortgage rate in the UAE?
FAB currently advertises fixed mortgage rates starting at 3.99% for qualifying fresh mortgage customers who transfer their salary to FAB and choose a FAB credit card. The published rate is 4.24% without salary transfer for the 1-, 2- and 3-year fixed options.
What is the FAB 5-year mortgage rate?
FAB currently publishes 4.19% for a 5-year fixed rate with salary transfer plus a FAB credit card, and 4.44% without salary transfer, subject to the stated conditions.
Does FAB offer a fixed mortgage rate?
Yes. FAB currently offers fixed-rate periods of 1, 2, 3 and 5 years for its UAE residential mortgage product.
What happens after the FAB fixed mortgage period?
The mortgage moves to the applicable variable-rate structure under your mortgage agreement. FAB currently states that the subsequent rate for salary-transfer customers using a FAB credit card is equivalent to 3-month EIBOR + 1.50%, subject to the stated minimum, while the published formula for non-salary-transfer customers is 3-month EIBOR + 1.89%, subject to the stated minimum.
Can I get a FAB mortgage without transferring my salary?
FAB publishes separate mortgage rates for customers without salary transfer. The current 1-, 2- and 3-year fixed rates shown on its website are 4.24%, compared with 3.99% for the salary-transfer plus FAB credit-card option.
How much of a property can FAB finance?
FAB currently states that first-time buyers can receive financing of up to 85% of the property value, subject to applicable conditions.
Does FAB offer mortgages to non-UAE residents?
Yes. FAB has a separate mortgage product for non-UAE residents buying investment property in the UAE. The bank currently states financing of up to AED 10 million and up to 50% of property value, subject to conditions.
Does FAB allow mortgage early settlement?
Early settlement is subject to the applicable mortgage terms and charges. FAB also states that some current mortgage-transfer offers include an early-settlement-fee refund for qualifying buyouts. Check your specific offer before settling or transferring the mortgage.